








Property Deposit Fraud: The risk every homebuyer must know
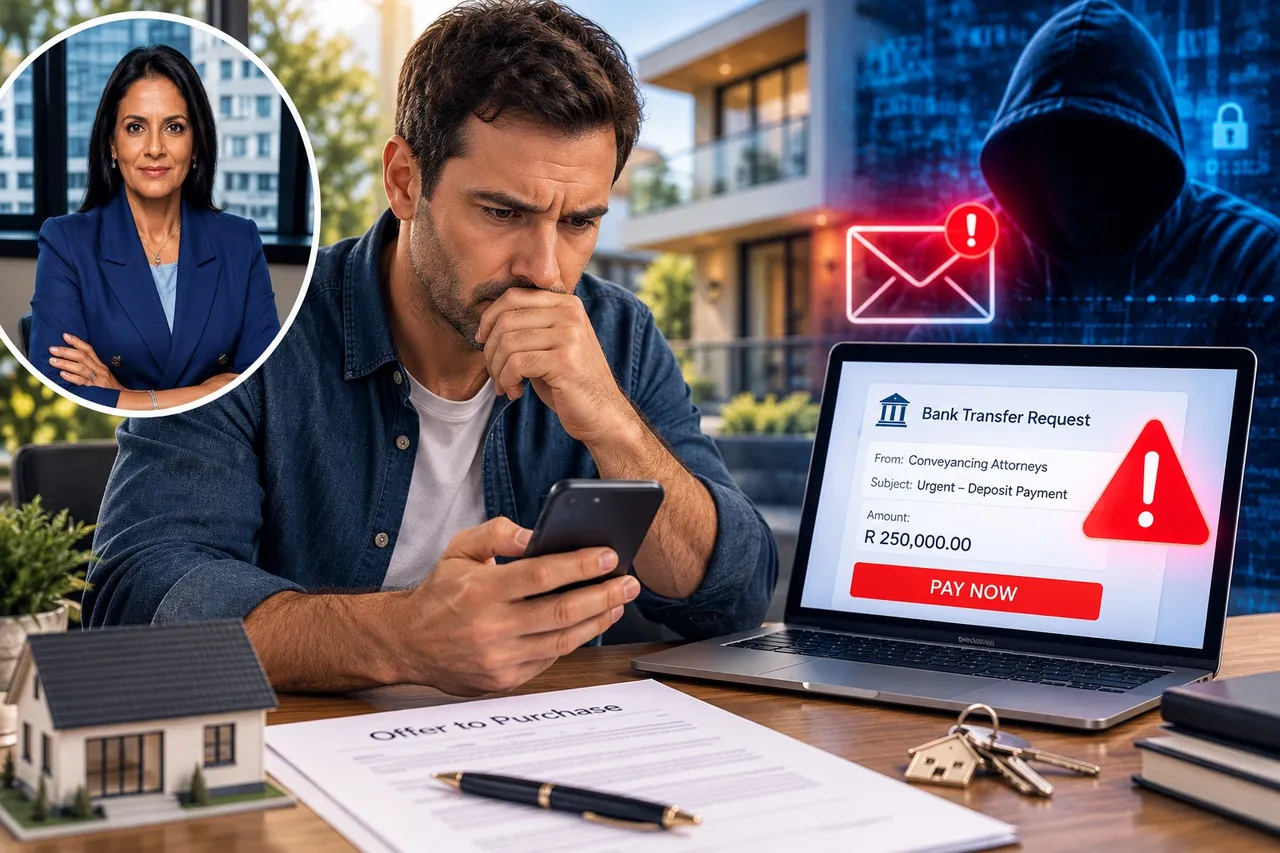
- Property deposits can represent years of savings, yet fraudulent payment instructions can put buyers’ money at risk within minutes.
- SABRIC reported R595.9 million in losses linked to fraudulent home and mortgage loan applications in 2025.
- Buyers must verify banking details independently and understand where their deposits are held, managed and protected until transfer.
Every October, Cyber Awareness Month reminds South Africans to strengthen passwords, avoid suspicious links and protect their personal information. But one of the most financially significant online transactions many consumers will ever make receives far less attention: paying a deposit on a property.
For homebuyers, transferring hundreds of thousands of rand can be an anxious moment. The Offer to Purchase has been signed, attorneys are preparing the transfer, banks are processing finance and several parties may be communicating simultaneously. It is also a moment when criminals can exploit urgency, confusion and misplaced trust.
Jackie Smith, CEO of Buyer’s Trust, a bank-hosted property deposit solution, believes the property industry needs to place much greater emphasis on protecting buyers at this critical stage.
“For a homebuyer, the most significant online transaction and therefore the moment they’re most vulnerable to fraud; happens after an Offer to Purchase is accepted and they’re asked to transfer their deposit,” says Smith.
“A property deposit is not a routine payment. It can represent years of saving, sacrifice and planning. Yet the moment of transfer happens at one of the busiest and most emotionally charged stages of the homebuying journey, when buyers are trying to keep the transaction moving while responding to instructions from multiple parties.”
Her warning is particularly relevant during Cyber Awareness Month, when attention often centres on everyday online security rather than the substantial sums changing hands in property transactions.
“Fraudsters understand this pressure,” Smith adds. “They look for moments where money, urgency and trust intersect.”
South Africa’s Cybercrime Risk is already sky-high
South Africa’s exposure to financial fraud is substantial, and property transactions are not immune. According to SABRIC’s 2025 Annual Banking Crime Statistics Report, fraudulent home and mortgage loan applications accounted for R595.9 million in reported losses during 2025.
The report also recorded approximately R2.4 billion in digital banking crime losses. These are different fraud categories, rather than a single measure of property deposit fraud, but together they illustrate the scale of financial crime affecting South African consumers and financial institutions. The broader digital fraud environment is also concerning.
Research published by TransUnion identified South Africa as having the highest rate of suspected digital fraud among the African countries analysed in 2025, with approximately 3% of consumer transactions flagged as potentially fraudulent.
Meanwhile, INTERPOL’s African Cyberthreat Assessment Report 2026 highlights the increasing sophistication of cybercrime, including AI-assisted deception, stolen credentials and social engineering.
For property buyers, the danger is particularly serious because transactions involve large payments and an extensive exchange of sensitive information. Smith explains that modern property transactions rely heavily on digital communication.
“Banking details, documents, instructions and confirmations often move over email, creating multiple points where criminals can intercept, impersonate or manipulate the process,” she says.
A fraudster who successfully impersonates a conveyancing attorney, estate agent or another trusted party may convince a buyer to transfer a deposit into an account controlled by criminals.
By the time the deception is discovered, recovering the money can be extremely difficult.
Personal information makes property scams more convincing
Property scams are becoming harder to recognise because criminals can use genuine personal and transaction details to make fraudulent instructions appear legitimate.
A September 2026 cybersecurity incident involving RelyComply, a third-party identity verification provider used by financial services businesses, illustrates the importance of protecting personal information throughout the property finance process.
Information such as names, identity numbers, contact details, addresses and banking details can be valuable to criminals if exposed. When combined with details about a property purchase, this information can make a fraudulent email, telephone call or payment instruction appear far more convincing.
A buyer might receive an email that appears to come from the transferring attorney, refers to the correct property and requests payment shortly before a genuine transaction deadline. The message may look professional, contain accurate details and even appear within an existing email conversation. That familiarity does not establish that the payment instruction is genuine.
“That is what makes these scams so dangerous,” says Smith.
“The instruction can feel legitimate because it arrives at the right moment and contains enough accurate information to lower the buyer’s guard. Buyers should not treat familiarity as proof of safety.”
For buyers, the lesson is straightforward: never rely solely on an email, WhatsApp message or familiar-looking document when transferring a property deposit.
Banking details should be independently confirmed using a verified telephone number obtained from a trusted source, rather than contact details supplied in the payment instruction itself. Any unexpected change in banking details should be treated as a warning sign until independently verified.
Deposit safety does not end at the point of payment
Avoiding a fraudulent payment instruction is essential, but protecting a property deposit involves more than ensuring that money reaches the intended account. Once a deposit has been paid, buyers should understand exactly what happens to their funds while the property transfer is being finalised.
This is an important distinction because a property transaction can take weeks or months to complete. During that period, the buyer may have a substantial amount of money held by another party.
The central questions are not simply whether the payment was successful, but whether the deposit arrangements are transparent, properly documented and consistent with the sale agreement.
Smith believes buyers should be asking more detailed questions before transferring their money. “Cyber safety in a property transaction is not only about spotting a suspicious email,” she says.
“It is also about making sure the buyer understands the process they are paying into. When a deposit is transferred, the buyer should know where it will be held, whose name the account is opened in, what records they will receive, whether interest will accrue and what happens if the transaction does not go ahead.”
These questions matter because deposits may be held under different arrangements, depending on the transaction and the contractual instructions. Buyers should know who is responsible for administering the funds, what documentation confirms receipt and how the money will be dealt with if the sale is delayed or cancelled.
They should also understand any applicable interest arrangements and the conditions governing the release or refund of the deposit.
A successful bank transfer does not, on its own, establish that every aspect of the deposit arrangement is secure or properly understood.
The deposit process needs the same attention as the payment itself
For Smith, Cyber Awareness Month should encourage the property industry to move beyond general warnings about suspicious emails.
Consumers also need greater transparency about the systems used to receive, hold and administer their deposits. “The answer is not for buyers to become cybersecurity experts overnight,” she says.
“The answer is to make sure the deposit process is structured, transparent and properly documented from the beginning.”
Buyer’s Trust offers a bank-hosted deposit arrangement in which, according to the company, the buyer’s deposit is placed in an account opened in the buyer’s own name.
The company says buyers receive regular statements and that funds are held in an interest-bearing account while transfer is pending.
This model is intended to give buyers greater visibility over where their money is held, how it is managed and what interest is earned during the transaction.
Regardless of the deposit solution used, homebuyers should understand the account arrangements, applicable safeguards, contractual terms and the responsibilities of the parties handling their funds.
Five checks before paying a property deposit
- Verify banking details independently.
Telephone the transferring attorney or authorised recipient using a previously verified number before making payment. - Question unexpected changes.
Treat last-minute changes to banking details or urgent payment requests as potential fraud indicators. - Confirm where the money will be held.
Understand the account arrangements, who controls the funds and the terms under which they may be released. - Request proper documentation.
Obtain written payment instructions, proof of receipt and information about statements and interest arrangements. - Understand what happens if the sale falls through.
Check the Offer to Purchase and deposit provisions so that you know when a refund may be due and whether any deductions could apply.
Protecting the biggest payment of your property journey
Buying a home should be an important financial milestone, not an opportunity for criminals to steal years of savings. As property transactions become increasingly digital, buyers, estate agents, conveyancers and financial institutions all have a role to play in strengthening payment security and improving transparency.
Cyber Awareness Month is an opportunity to remind consumers that the biggest financial risks do not always begin with suspicious websites or unfamiliar messages. Sometimes they arise during an entirely legitimate transaction, when a buyer receives what appears to be an ordinary instruction to pay a property deposit.
Smith believes buyers should expect stronger safeguards throughout the process. “When a buyer is transferring one of the largest sums of money they may ever pay, security cannot depend on trust alone,” she concludes.
“There should be clear records, proper safeguards and confidence that the deposit is being managed in the buyer’s best interests from payment through to transfer.”
The message for South African homebuyers is simple: verify before you pay, understand where your money is held and never allow urgency to override financial security.