








Furnished or Not? Insurance Essentials for Landlords
Main takeaways
- Furnishing levels (unfurnished, semi, or fully) impact insurance needs
- Short-term rentals like Airbnb face stricter liability risks
- Tenants must insure their own possessions, landlords are not liable.
Furnished, Semi-Furnished or Unfurnished? Here’s What You Need to Know
South Africa’s rental market is heating up. According to the PayProp Rental Index, national rental growth reached 5.6% in Q1 2025, the strongest quarterly gain in nearly eight years.
This spike in demand has sparked a boom in long- and short-term rentals, including Airbnb listings, student lets, and B&B conversions. But as more properties shift into rental mode, a key question for landlords and investors arises:
How does the level of furnishing affect your insurance risk – and cover?
We break down the pros and cons of each property setup, and the insurance essentials that go with them.
1. Unfurnished Rentals
What it means: No movable items, tenants supply their own appliances and furniture.
Landlord’s responsibility
- Building insurance covering structural damage (fire, storm, geysers).
- Public liability cover for third-party injuries on-site.
- Protect against claims like roof tiles damaging vehicles, or faulty plumbing harming tenant property.
“If a property isn’t maintained and causes damage, the landlord must have liability cover in place,” says Ryno de Kock, Head of Distribution at PSG Insure.
Tenant’s responsibility
- Contents insurance for personal belongings (e.g. electronics, furniture).
- Landlord policies don’t cover tenant possessions.
“If a geyser floods your apartment and ruins your TV, your landlord’s policy won’t help. You need your own cover.”
2. Semi-Furnished Rentals
What it means: Basic appliances and some furniture included, e.g. fridge, washer, bed, table.
Landlord’s responsibility
- Building cover, plus contents insurance or clear inventory clauses.
- Document all items and their replacement values in the lease.
- Decide whether landlord or tenant insures supplied items.
Tenant’s responsibility
- Insurance for personal items and potentially, listed landlord furniture.
“Responsibility can shift depending on the lease. Tenants may be liable for damages to included furniture,” says de Kock.
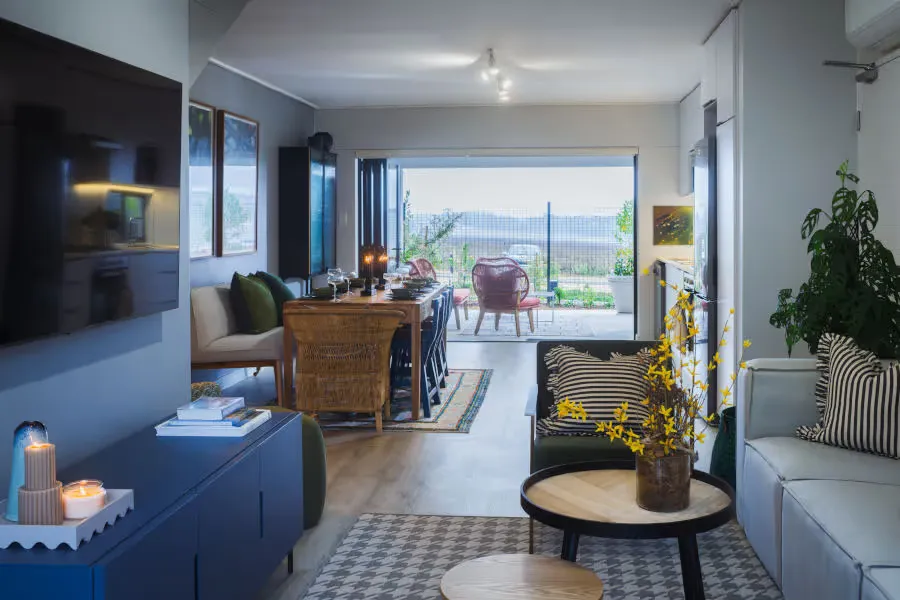
3. Fully Furnished & Short-Term Rentals (e.g. Airbnb)
What it means: Property includes all furniture, appliances, décor, ideal for short stays.
Landlord’s responsibility
- Comprehensive contents insurance at current replacement values.
- Update inventory regularly.
- Public and product liability insurance, especially if meals or staff are involved.
“If you’re hosting international Airbnb guests, liability claims can be filed in foreign currency — commercial cover is critical,” says de Kock.
Risks to consider
- Airbnb’s cover is limited to hosts who live on the property with under 6 guests.
- Theft without forced entry may not be covered.
- Damages caused by guests may be excluded under standard domestic policies.
Airbnb advises hosts: “Hosts should maintain their own homeowners or renters insurance to cover personal liability.”
Tenant’s responsibility (where applicable)
- Personal items still require separate cover designer gear, tech, etc. won’t be insured by the landlord.
Key Insurance Consideration
- Always assess who owns which items and who is liable for them.
- Review policies to avoid underinsurance or exclusions, especially with short-term guests.
- Add disclaimers to Airbnb/B&B listings to protect yourself legally.
- If you provide food or have employees, get product and personal liability cover.
Tailored Cover is Key
Whether your rental is empty, partially furnished, or packed with premium finishes, insurance isn’t one-size-fits-all. The type of cover you need changes with the level of furnishing and the use of the property.
“With the right policies and expert advice, property rentals can be extremely profitable,” says de Kock. “Just make sure you’re protected against the specific risks you face.”