





The energy decision that could change your property yield
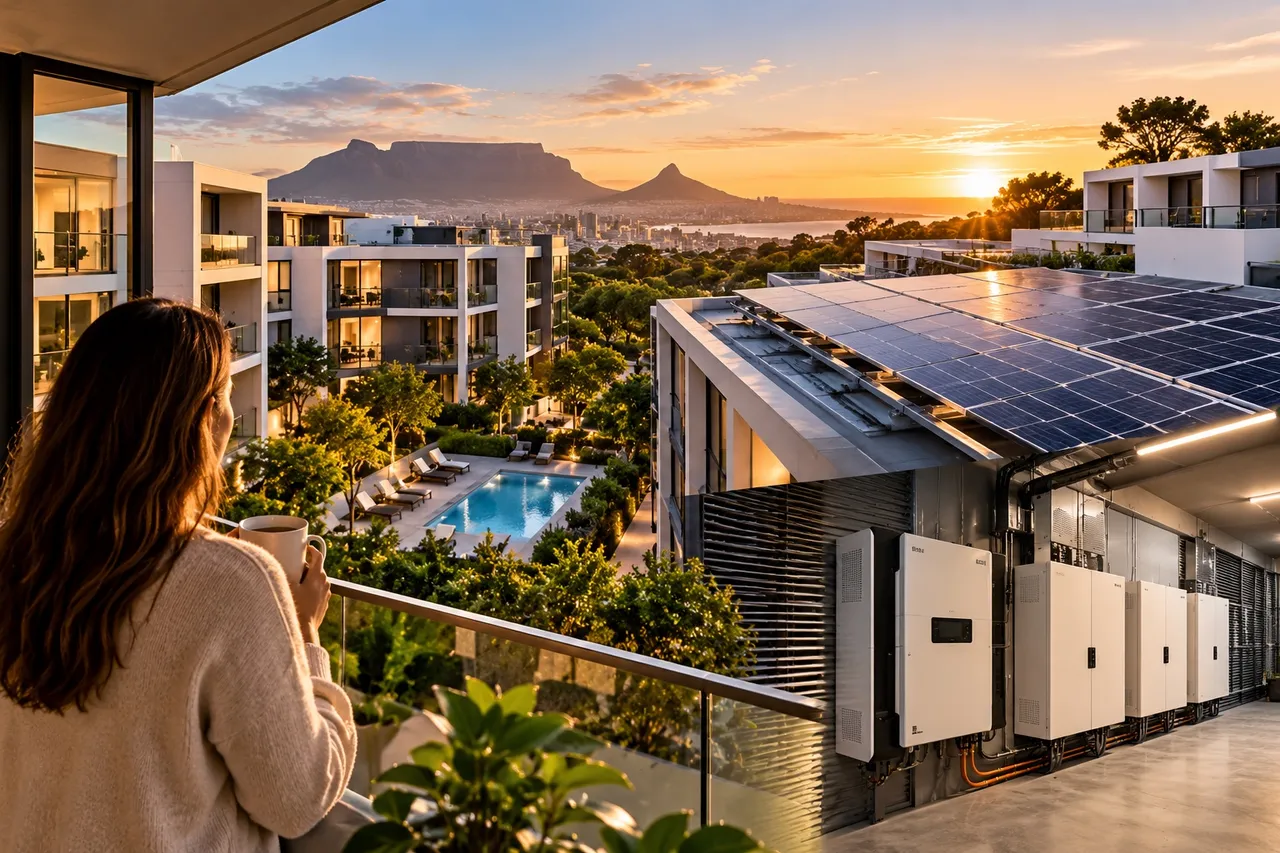
Electricity is no longer simply a utility expense. In sectional-title schemes, it can affect levies, affordability, lettability and ultimately an investor’s return.
- Electricity affects both sides of the investment equation: what residents pay to occupy a unit and what owners pay to hold it.
- Energy structures can affect levies, special levies, scheme reserves and resident affordability, but investors rarely control these decisions individually.
- Before approving any energy proposal, investors should establish exactly what changes, who carries the risk and who ultimately pays the electricity bill.
Electricity is becoming an investment issue
Buy a sectional-title property and most of the investment equation can be interrogated before signing.
You can calculate the bond repayment, examine comparable rentals, analyse vacancy levels, scrutinise the body corporate’s financial statements and reserves, check the levy history and assess the fundamentals of the area. Electricity is becoming harder to contain.
Rising municipal tariffs increase the scheme’s operating costs. Ageing electrical infrastructure creates maintenance and capital risks. Outages affect the experience of living in the development, while the cost of alternative energy infrastructure can potentially result in additional capital expenditure.
For the investor, there is another complication: you may carry the financial consequences without having individual control over the decision.
In sectional-title schemes, major energy decisions are typically made collectively at scheme level. That means investors need to start treating a scheme’s energy strategy as part of their investment due diligence, not merely as an operational matter for trustees and managing agents.
The two ways electricity affects an investor
Electricity reaches an investor from two different directions.
1. What it costs a resident to occupy the property
The resident’s electricity account may not appear directly on the investor’s income statement, but it forms part of the property’s total occupancy cost.
For a tenant comparing two similar apartments at similar rentals, electricity costs can become a differentiator. As household budgets tighten, investors therefore need to look beyond asking rentals.
The real affordability equation is closer to: Rent plus electricity plus water plus other utilities = Total cost of occupation.
If one scheme can materially reduce that total cost, it may strengthen its competitiveness, tenant retention and lettability.
2. What it costs the investor to own the property
Then there is the electricity consumed by the scheme itself. Common-area lighting, lifts, pumps, security systems, gates and other shared infrastructure all require energy.
Those expenses sit within the body corporate’s operating costs and are ultimately funded by owners through levies. As electricity tariffs increase, pressure can therefore work its way through the scheme’s budget and eventually into an investor’s cost of ownership.
One affects what the property costs to occupy. The other affects what it costs to own. For investors, both matter.
Not every energy proposal changes the same things
This is where investors need to look beyond the word “solar”.
Installing solar panels does not necessarily remove the scheme’s exposure to electricity costs or transfer its financial responsibilities.
Under a conventional solar solution, the system may reduce the cost of part of the electricity consumed by the scheme. However, the body corporate can remain responsible for the municipal or utility account, residual grid consumption and the associated financial exposure. An Energy as a Service (EaaS) model takes a different approach.
Under Blockpower’s proposed model, the company funds and manages the scheme’s energy infrastructure and assumes responsibility for settling the electricity bill.
Depending on the requirements of the scheme, the infrastructure can incorporate solar generation, battery storage, smart prepaid metering, monitoring and energy management.
For the body corporate, the proposition is that there is:
- No upfront capital contribution;
- No debt incurred to acquire the energy infrastructure;
- No ownership of the energy assets;
- No insurance liability for those assets; and
- Ongoing operation and maintenance of the system by the provider.
As Kyle Bohnsack, Managing Director of Blockpower, puts it:
“A scheme shouldn’t have to become an energy company to keep the lights on.”
That distinction matters. Investors shouldn’t simply ask: “How much solar are we getting?” They should ask: “What financial exposure is actually being transferred or reduced?”
What that can change for an investor
An energy intervention becomes relevant to property investment when it changes income, expenses, capital requirements or risk. There are several potential effects.
A more affordable property to occupy
According to Blockpower, residents can save up to 30% on prepaid electricity where NERSA-approved reseller rates apply.
The landlord doesn’t receive that saving directly. But if the resident’s total monthly cost of occupying the property falls, the unit potentially becomes more competitive against comparable properties.
That can matter for lettability and tenant retention. For investors, therefore, the question isn’t only: “Does this increase my rental?” It is also: “Does this make my unit easier to rent and retain a good tenant?”
Less exposure to special levies
Major maintenance and infrastructure expenditure can be particularly painful for sectional-title investors when a scheme’s reserves are inadequate.
Where an EaaS benefit is structured as upfront capital, future energy value can potentially be converted into funding that the body corporate can use for maintenance, repairs, upgrades or reserves.
That could reduce the need for owners to fund qualifying expenditure through a special levy. For a leveraged investor, avoiding an unexpected capital call can be significant.
Potentially lower pressure on levies
Another structure is to provide the body corporate with an annuity income stream. That income can support the scheme’s finances and potentially reduce pressure for future levy increases.
Again, investors need to be precise here. An additional income stream does not guarantee that levies will fall. The body corporate has many other expenses.
The investment question is whether the arrangement strengthens the scheme’s financial position and reduces one source of upward pressure.
Better-managed energy infrastructure
Energy systems don’t stop requiring attention once they are commissioned. Solar, batteries, metering and associated infrastructure require monitoring, maintenance and management.
Under Blockpower’s model, it remains responsible for operating and maintaining the system during the service term rather than transferring that responsibility back to the body corporate.
That potentially moves an operational and maintenance risk away from the scheme.
What investors should ask
Whether you’re considering buying into a sectional-title scheme or voting on an energy proposal in one you already own, investors should interrogate the numbers rather than simply voting for or against “solar”.
1. What does the scheme spend on electricity?
Ask for the actual number. Then compare electricity expenditure with the scheme’s total operating income and expenses.
If trustees, managing agents or the proposed energy provider cannot clearly quantify the existing cost base, it becomes difficult to assess whether the proposed solution genuinely improves it.
2. How much of total consumption does the solution address?
This is critical. A headline saving can sound impressive while applying to only one component of the scheme’s overall consumption.
Investors should establish: Current total consumption → consumption addressed → projected saving → net scheme-wide financial benefit.
The whole-scheme result matters more than the marketing percentage.
3. Is the scheme buying, financing or contracting for energy?
These are very different financial structures. Establish whether the body corporate is taking on debt, purchasing infrastructure, entering into a long-term service agreement or transferring certain responsibilities to the energy provider.
Then ask what happens if the scheme wants to exit the arrangement.
4. Who owns the infrastructure?
Ownership can bring maintenance, replacement, insurance and obsolescence risk.
Investors need to understand where those responsibilities sit throughout the agreement.
5. What happens when equipment fails?
Who repairs it? Who pays? What service levels apply? And what happens if performance is below what was originally projected?
6. What is the actual benefit to owners?
Is it:
- lower resident electricity prices;
- lower common-property electricity expenditure;
- an upfront capital benefit;
- recurring income for the body corporate;
- reduced infrastructure expenditure;
- reduced exposure to special levies; or
- some combination of these?
The proposal should quantify the benefits rather than simply describe them.
Who settles the electricity bill after signing?
This may be one of the most revealing questions an investor can ask: who is responsible for settling the scheme’s electricity account once the energy agreement becomes operational?
Why does it matter? Because it helps distinguish between a solution that merely reduces part of an electricity expense and one that changes where certain financial responsibilities sit.
Under Blockpower’s EaaS model, Blockpower says it assumes responsibility for settling the electricity bill.
That is fundamentally different from simply installing solar equipment while leaving the body corporate responsible for the remaining utility account.
Investors should establish precisely what “responsibility” means contractually, including which electricity accounts are covered, what remains payable by the scheme, how tariffs are determined and adjusted, how long the agreement runs and what happens on termination.
The headline benefit is important. The contract behind it is more important.
Energy now has a direct line to investor returns
Property investment ultimately comes back to three things: Income. Expenses. Risk.
Electricity increasingly touches all three. It affects what residents pay to occupy a property. It influences body corporate operating expenses. It can contribute to levy pressure. Infrastructure expenditure can result in capital calls. Reliability can affect the resident experience and, ultimately, the desirability of the scheme.
That means energy can no longer be relegated to the maintenance agenda at the next trustees’ meeting.
For prospective purchasers, the scheme’s energy position should increasingly form part of pre-purchase due diligence, alongside financial statements, levy history, reserve funds, maintenance plans and conduct rules.
For existing owners, the question isn’t simply whether an alternative-energy proposal sounds attractive. It is whether the proposal measurably improves the economics and reduces the risks of the scheme.
Because in sectional-title property, the investor may own the unit individually, but some of the decisions capable of influencing its return are made collectively. Energy is now one of them.