





Seeff urges SARB to hold rates steady
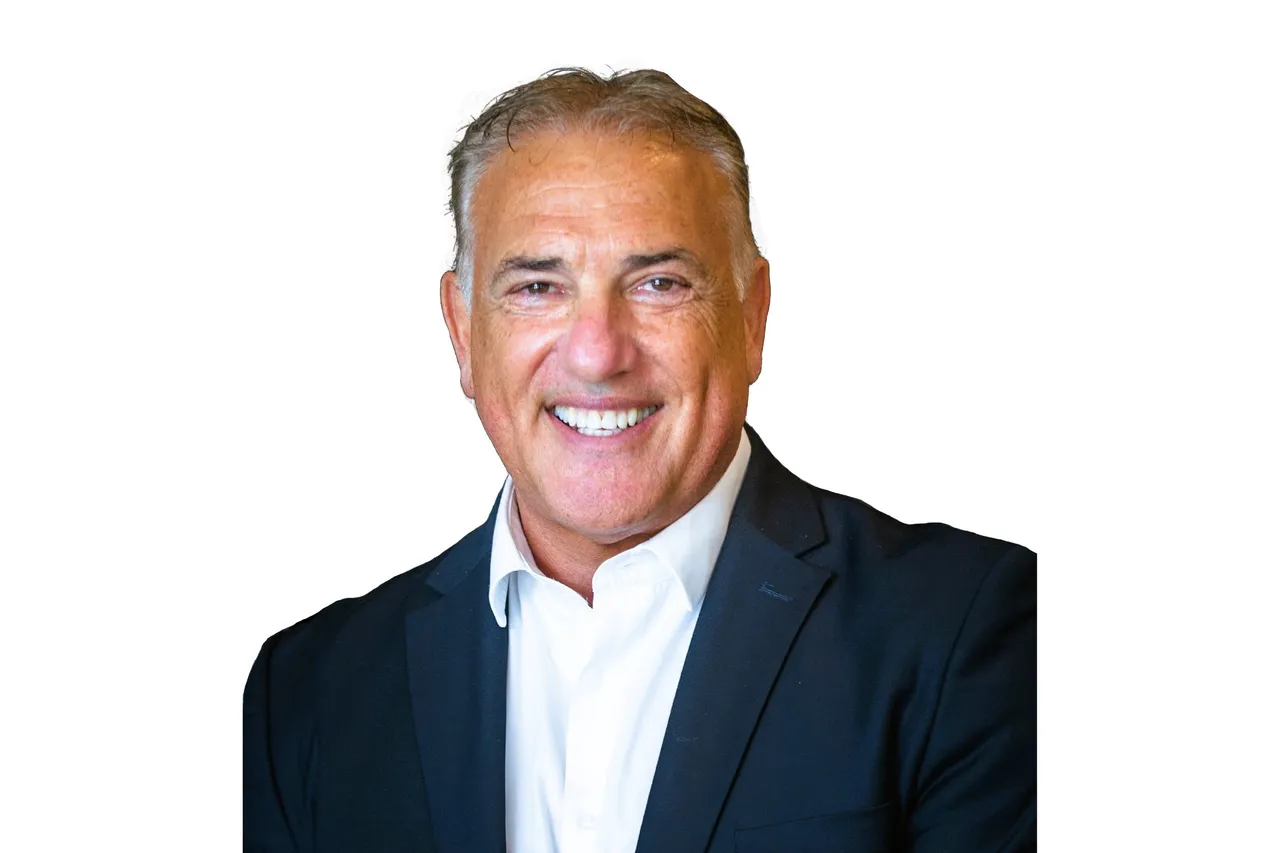
With South Africa’s interest-rate decision due on Wednesday, Samuel Seeff warns that another increase could weaken household finances, property activity and the broader economic recovery.
- Seeff warns another 25-basis-point increase would intensify pressure on bondholders, buyers and South Africa’s already weak economic recovery.
- He argues higher rates cannot resolve oil-driven inflation because the pressure originates in global supply conditions, not excessive domestic demand.
- Holding rates steady, he says, would protect confidence, affordability and property activity while giving temporary cost pressures time to ease.
With the South African Reserve Bank’s next interest-rate decision due on Wednesday, Samuel Seeff, chairman of the Seeff Property Group, has made an urgent call for the Monetary Policy Committee to leave the repo rate unchanged.
The decision comes at a sensitive point for the economy and property market. Global monetary policy has tightened, oil prices remain elevated and domestic inflation has increased, raising concerns that the Reserve Bank could implement another 25-basis-point rate hike.
Seeff argues that raising rates now would offer little protection against externally driven inflation while placing further pressure on consumers, homeowners, businesses and property investors.
His central message is straightforward: South Africa needs stability, not another increase in borrowing costs.
Why Seeff is calling for a hold
Seeff believes the latest inflationary pressure is being driven primarily by global supply-side forces, including elevated oil prices, rather than excessive domestic consumer demand.
An interest-rate increase may suppress local spending, but it cannot increase global oil supply or remove international cost pressures. It would, however, immediately raise borrowing costs throughout the domestic economy.
For property owners with variable-rate home loans, another increase would mean higher monthly bond repayments. For first-time buyers, it would reduce affordability and potentially weaken their ability to qualify for finance.
Developers and commercial-property investors would also face higher finance and holding costs, making some projects and acquisitions more difficult to justify.
According to Seeff, this creates a risk that monetary policy could impose more pain on the domestic economy without addressing the real source of the inflationary pressure.
Another increase would follow May’s hike
The Reserve Bank increased the repo rate by 25 basis points in May. A further increase on Wednesday would compound the pressure on households that are already absorbing higher food, transport, electricity and other living costs.
Even a relatively small rate increase matters when it is applied to a home loan over many years.
For existing bondholders, higher repayments reduce disposable income. For aspiring buyers, higher lending costs reduce the size of the bond they can afford. For investors, the effect can be felt through weaker cash flow, tighter yields and greater pressure on tenants whose household budgets are already stretched.
Seeff warns that these consequences could slow transaction volumes and weaken momentum in a property market that depends heavily on confidence and access to affordable credit.
Economic growth is already under pressure
The national economic growth outlook has reportedly been revised down from an initial projection of 1.4% at the beginning of the year to approximately 1.1%.
Although the change may appear modest, it represents a meaningful downgrade for an economy already struggling to generate sufficient growth, investment and employment.
Higher borrowing costs could place further pressure on consumer spending, business expansion and property-market activity.
When households spend more on servicing debt, they have less available for other goods and services. Businesses face a similar trade-off as the cost of funding working capital, equipment, expansion and property increases.
Seeff argues that South Africa’s monetary authorities should therefore weigh the broader economic consequences of another hike against the limited effect it may have on externally driven inflation.
What another hike could mean for property
A further rate increase could affect the property market in several ways:
- Monthly repayments would rise for homeowners and investors with variable-rate bonds.
- First-time buyers could qualify for smaller loans or delay purchasing.
- Highly leveraged investors could face weaker monthly cash flow.
- Developers would have to absorb higher finance and holding costs.
- Buyer confidence and transaction activity could slow.
- Financial pressure could increase the risk of arrears and defaults.
- Tenants could face pressure where landlords attempt to recover rising costs.
The effect would not be equal across the market. Highly indebted households and investors with tight cash-flow margins would be the most exposed.
Cash buyers and investors with lower levels of debt may find opportunities if market activity slows, but widespread financial pressure would not be positive for the sector as a whole.
Stability would support confidence
Seeff believes holding the repo rate steady would provide businesses, homeowners and investors with greater certainty while allowing time to determine whether the latest inflationary pressures are temporary.
A stable rate would not remove the pressure created by elevated living costs, but it would avoid adding another layer of financial strain.
For the property market, predictability matters. Buyers need confidence that they can afford repayments, developers need greater certainty when modelling projects and investors need a reliable basis for calculating cash flow and returns.
Maintaining the current rate would allow the market to adjust without the additional shock of another increase.
What property investors should do now
Regardless of Wednesday’s decision, investors should prepare for continued interest-rate volatility. They should:
- Stress-test repayments against at least another one-percentage-point increase.
- Maintain sufficient cash reserves for vacancies and unexpected expenses.
- Recalculate net yields using current finance and operating costs.
- Avoid relying on future rate cuts to make a deal viable.
- Review whether rental income adequately covers debt and recurring expenses.
- Negotiate interest rates and lending terms with more than one bank.
A property deal should remain sustainable under realistic pressure — not only under the most optimistic forecast.
The bottom line
Seeff’s appeal is not for artificially cheap money. It is a call for the Reserve Bank to distinguish between persistent domestic inflation and temporary global cost shocks before placing further pressure on an already constrained economy.
Another increase may demonstrate a firm stance on inflation, but it would also raise repayments, weaken affordability and risk slowing economic and property-market activity at a vulnerable moment.
For homeowners and investors, Wednesday’s decision will have immediate consequences. Holding the repo rate steady would provide a measure of stability, protect confidence and give South Africa’s economy more room to recover.